 Bilal Hassan·4d ago
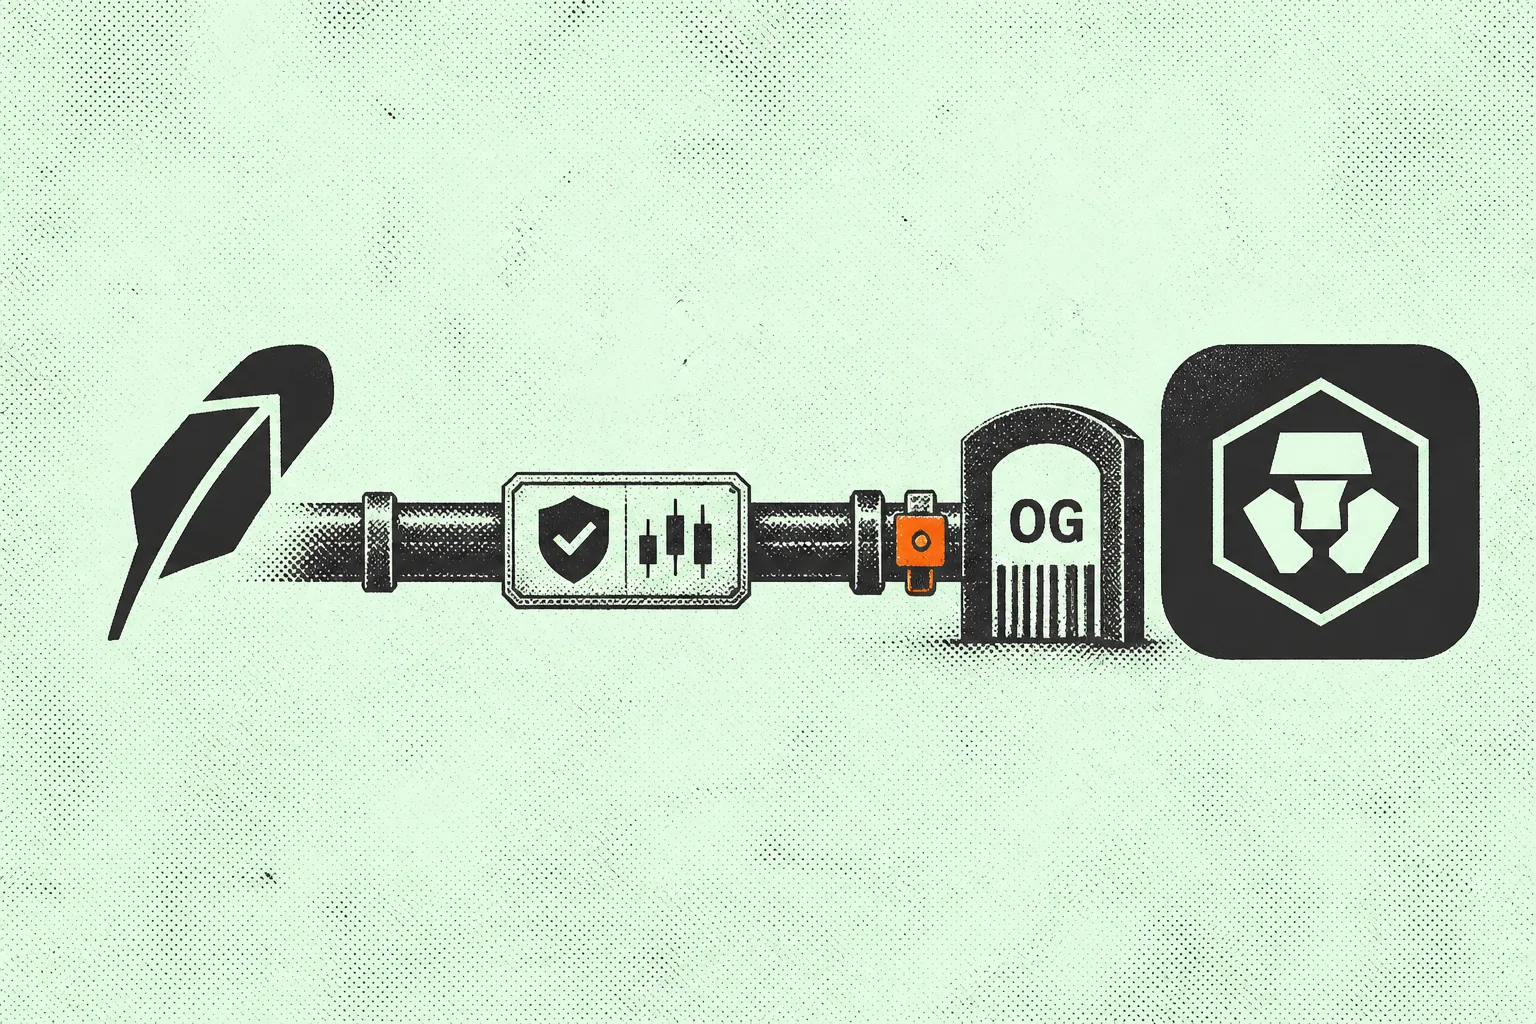
This Robinhood Crypto.com partnership is distribution buying venue liquidity with equity, not a clean vendor add. Robinhood already routes event contracts across several CFTC venues. Stakes in Crypto.com and OG.com tie the brokerage’s prediction growth to someone else’s exchange and clearing stack. Score it as a capital-backed routing deal, not a software integration.
Per Robinhood’s September 8, 2026 newsroom post, Robinhood Markets will hold equity in Crypto.com and in OG.com after OG.com’s spin-off. The stake is priced to Citadel Securities‘ recent Crypto.com Group mark at a $20 billion valuation. Stake size stays undisclosed. From September 8, Robinhood routes selected football event contracts to OG.com. The path runs through Crypto.com’s CFTC-regulated exchange and clearinghouse, Crypto.com | Derivatives North America (CDNA) / OG.com. Contracts still also route to Kalshi, ForecastEX, and Rothera.
The non-obvious read is not “football season is back.” Robinhood pays for inventory depth with ownership. Then it routes retail flow into that venue. Citadel set the public Crypto.com Group reference. Robinhood clips equity to that mark and adds a live football path on day one. The book still includes Rothera (Susquehanna JV), Kalshi, and ForecastEX. Venue diversity is the public story. Equity is the private lever.
Robinhood’s numbers explain the urgency. In Q2 alone, 13.6 billion event contracts traded on the app; World Cup flow topped 5 billion. Independent coverage puts Q2 prediction revenue near $156 million, ahead of equities transaction revenue and crypto on the same books. When a line outruns equities fees, you buy a seat; you do not rent liquidity forever.
Who needed this more? Robinhood needed football depth and another CFTC rail before midterms. Crypto.com and OG.com needed Robinhood retail flow to prove OG.com as a liquid derivatives venue. Mutual need. Robinhood still owns the scarcer asset: the app and the routing switch.
Webinar Test: Joint product? Yes, narrowly: live event-contract routing to a named CFTC exchange and clearinghouse. Pass as a shipped rail. Fail as a fully disclosed economics package.
The release prints valuation alignment and a September 8 football start. It does not print percent ownership, cash vs. in-kind, lockups, or venue-share economics. Treat that blank as diligence. State gambling fights already squeeze sports event contracts: Nevada extended a Kalshi ban; New Jersey asked the U.S. Supreme Court whether states can regulate sports contracts on CFTC venues. More football inventory into OG.com does not erase that fight. It concentrates volume into legal weather Robinhood does not control alone.
If you’re a founder building prediction rails: Equity-for-flow is the emerging partnership template. It shows up when a retail front end outgrows any single venue. Price distribution and clearing as the product.
If you’re an operator competing with OG.com or Kalshi: Assume Robinhood keeps a multi-venue book. Win on coverage and sports-state resilience, not exclusive logos.
If you’re an investor: Separate app revenue from venue economics. $156 million on Robinhood does not disclose what OG.com keeps. Demand the stake math before you underwrite ownership quality.
I’ll believe this is more than football inventory when two proofs land. Robinhood must route midterm contracts to OG.com. Either party must also disclose venue-share or fee economics. If the next proof is only more game SKUs with the same silent equity line, the thesis stays distribution with an undisclosed warrant.
The general law: When a retail broker takes equity in the CFTC venue it routes into, score ownership and routing economics first. Product proof is live contract flow. Partnership quality is the disclosed share of that flow.
Related News
Explore more